First-Time Buyer
Mortgage Rates Are Shifting: A Plain-English Guide for First-Time Buyers Eyeing 630 Rogers Rd.
Published September 28, 2026
The mortgage market keeps shifting, and there is one message that matters more than any headline right now, especially if you are a first-time buyer in Toronto: waiting for the "perfect" rate can be risky when the market is moving quickly. This guide is written in plain English, no jargon, no crystal ball. Just what is happening with mortgage rates in Toronto, why pre-approval beats waiting, and how a move-in-ready home like 630 Rogers Rd #21 takes the guesswork out of your first purchase.
I know rate talk can feel like it was written for economists. So let me translate what is actually going on, what it means for your budget, and the one step that protects you either way.
What's Happening with Rates
You do not need to follow every financial news headline. Here is the simple version of what is driving today's rate conversations:
Higher oil prices add pressure. When oil prices climb, they feed into the cost of everything from fuel to shipping, and that nudges inflation higher.
Inflation concerns keep things tense. When the cost of living feels uncertain, lenders price mortgages more cautiously, and caution quietly pushes rates up.
Bond yields are running elevated. Fixed mortgage rates are funded with government bonds, so when bond yields stay high, fixed rates tend to follow. It is the hidden engine behind the numbers you see.
Bank of Canada expectations have shifted higher too. Market watchers are adjusting their bets, and that tone ripples through the rates lenders actually offer.
Notice what I am not doing here: I am not quoting a number, and I am not telling you rates will definitely go up or down. Nobody can promise that. What I can tell you honestly is that the pressure is real, the direction is being watched closely, and that makes today's terms worth protecting.
Why Waiting for the Perfect Rate Is Risky
Here is the trap: in a market that is moving quickly, the perfect rate may never actually show up. You wait for a number that looks slightly better, and while you wait, the rate that was right in front of you can slip away. It is a waiting game where the prize keeps moving, and you are the only one standing still.
The smarter play for a first-time buyer is refreshingly simple: get pre-approved now. A pre-approval locks in today's terms for a set window, usually 90 to 120 days, so today's numbers are protected while you keep looking. And when the right home appears, you are ready to move on it, not scrambling to get your financing together at the last minute. You cannot control where the market goes next, but you can absolutely control whether you are ready for it.
What This Means for You
This is where the home itself does some of the work for you. A move-in-ready home like 630 Rogers Rd #21 takes two risks off the table at once: the renovation risk and the waiting game.
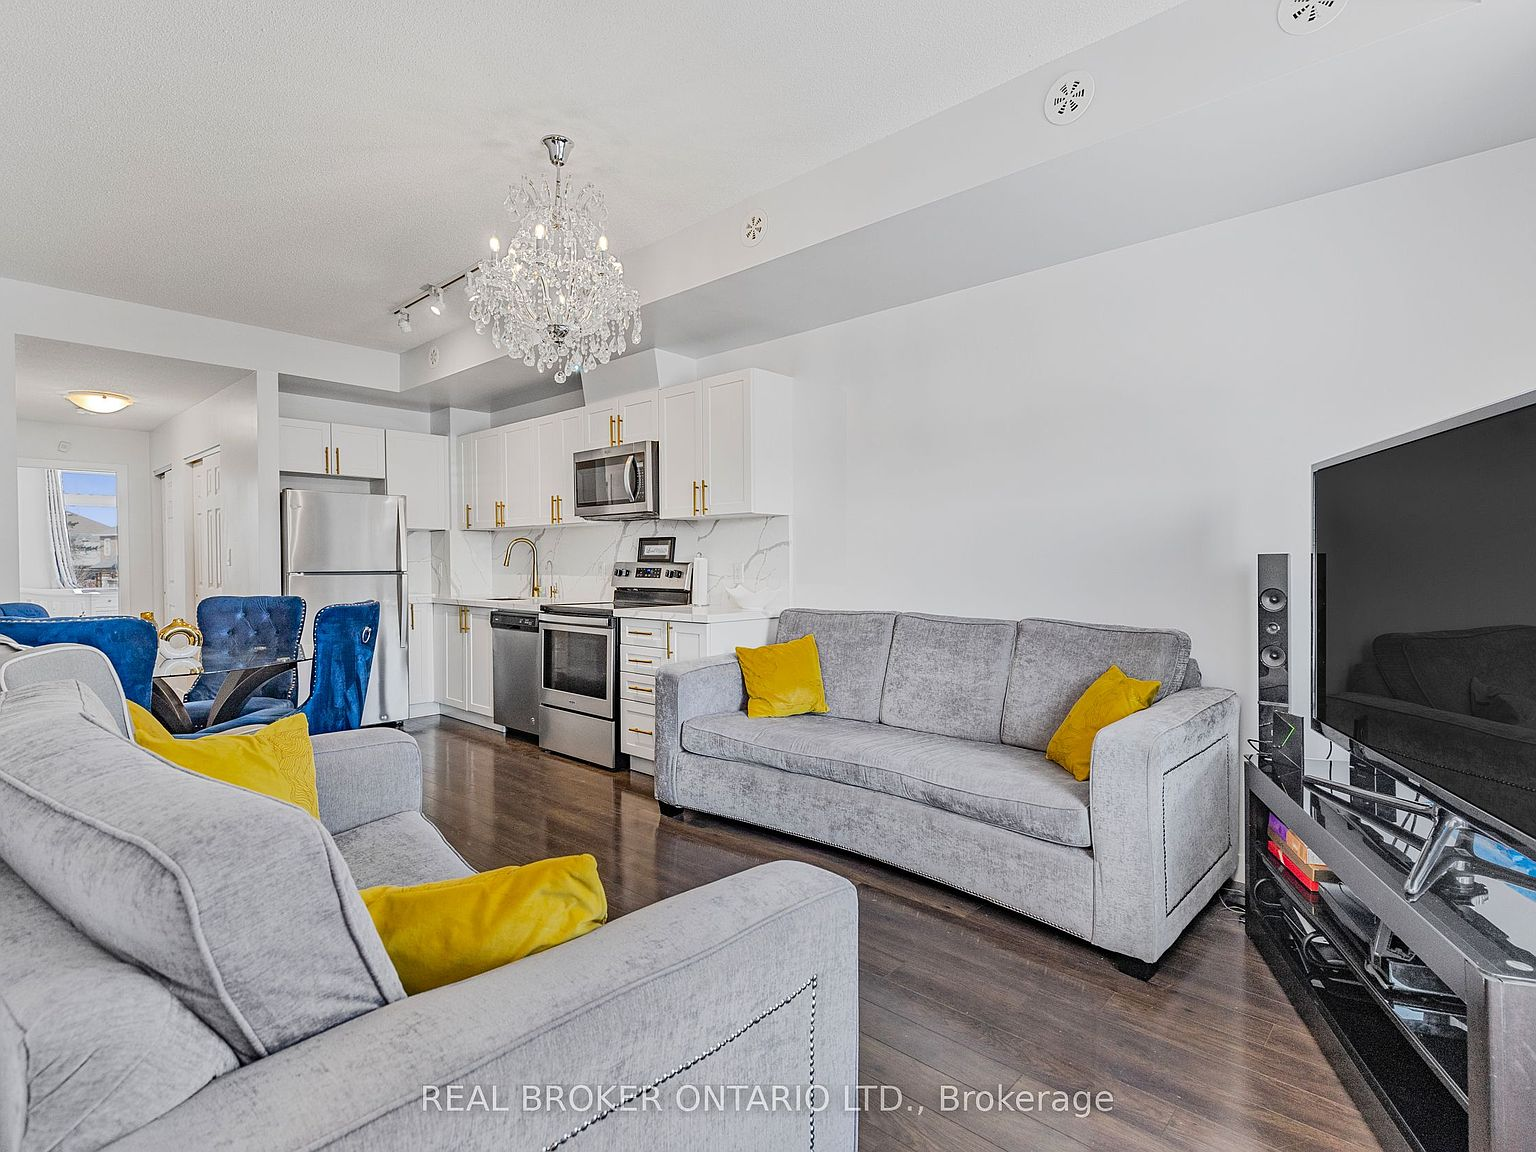
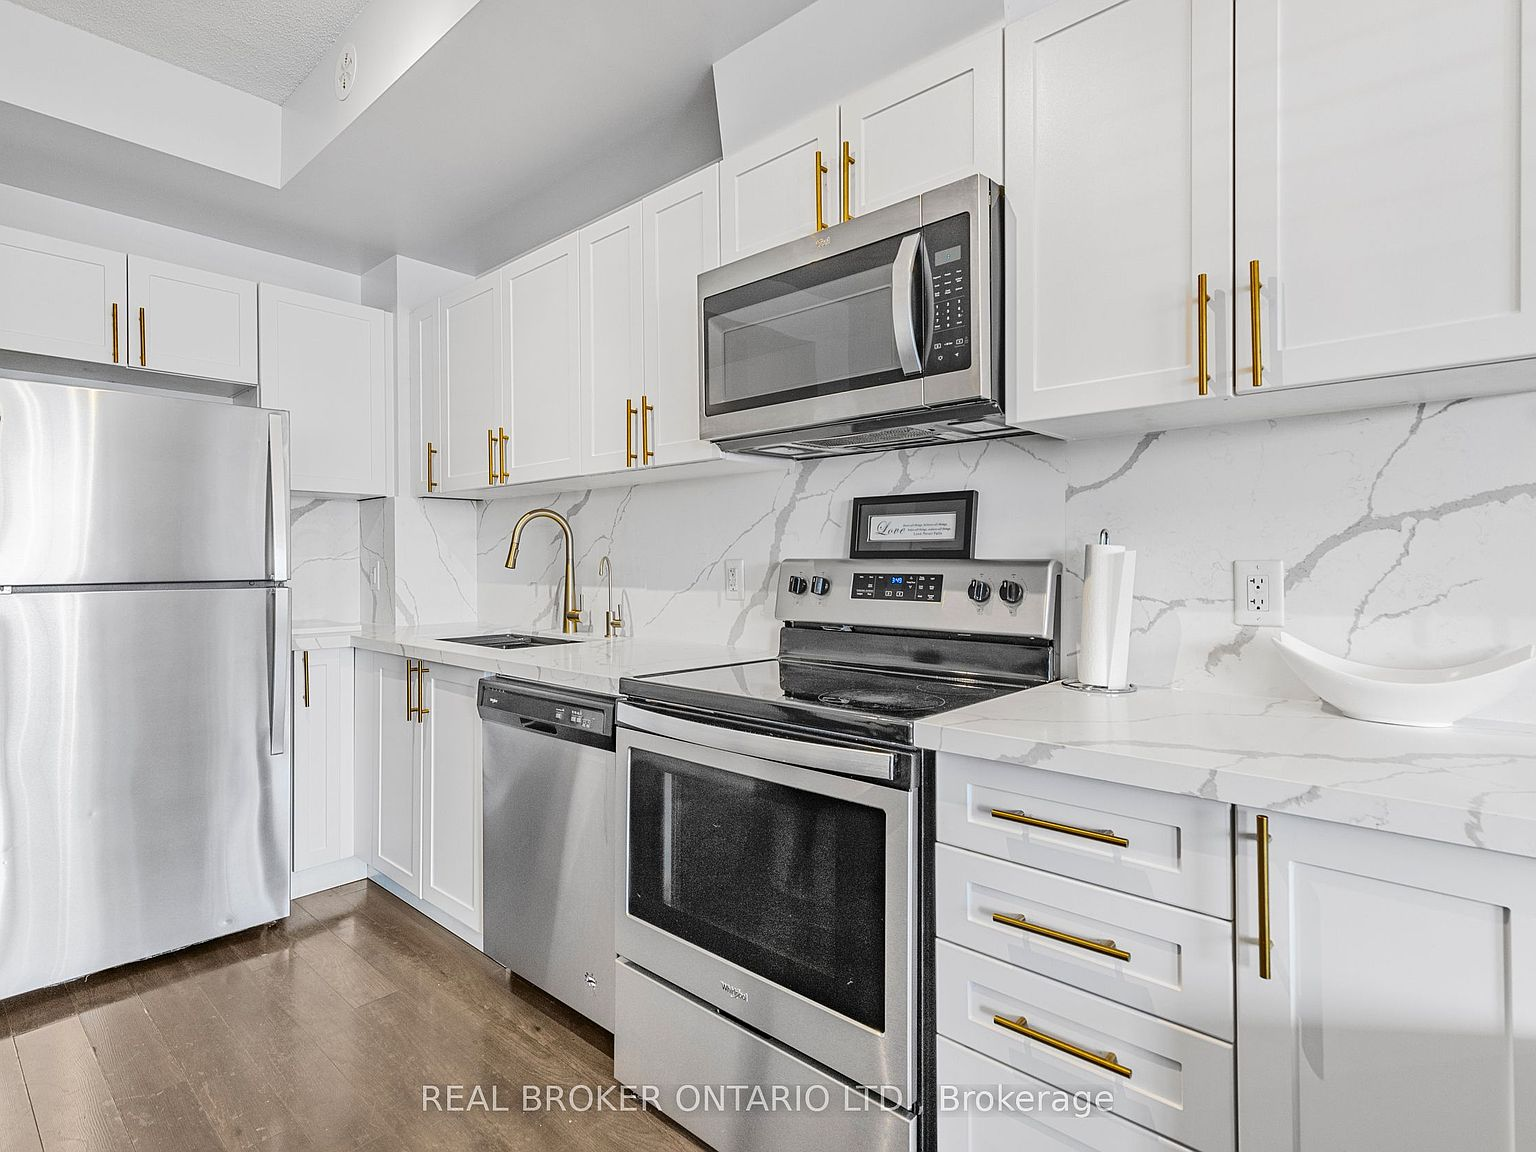
This 2-bedroom, 1-bath main-floor townhome, built in 2019 and cared for by its original owner, is ready to move into today: brand new flooring throughout, quartz countertops, stainless steel appliances, full-size in-unit laundry, and one owned parking spot, all just steps from transit, shops, and parks. No renos to budget for, no six-month wait before you can live in it, and no surprises eating into the payment you planned. You can act now with confidence, and that protects you against tomorrow's rate moves in a way no prediction ever could, because the payment you calculate today is the payment you get. You can stroll through the photo gallery or read the full tour of the home in this earlier post.
A Trusted Partner for Pre-Approval
Pre-approval does not have to be intimidating, and you should never feel pressured into a process you do not understand. M2 Mortgage Team is Tory's trusted mortgage partner, and they walk first-time buyers through pre-approval in plain language. They will tell you exactly what you qualify for, hold today's rate for your shopping window, and answer every question without the jargon. It is free, there is no obligation, and knowing your number is the single most protective step you can take in a shifting market. Start at m2mortgageteam.ca.
Common Questions, Straight Answers
Are fixed mortgage rates going up?
Fixed mortgage rates are under upward pressure right now because of higher oil prices, inflation concerns, and elevated bond yields, which lenders use to price fixed mortgages. No one can promise an exact direction, and anyone who does is guessing. But when the pressure is real, protecting today's rate with a pre-approval is rarely a move you regret.
What is a bond yield?
A bond yield is basically the interest a government bond pays its investor. Mortgage lenders fund fixed-rate mortgages using these same bonds, so when bond yields climb, fixed mortgage rates tend to climb with them. Think of bond yields as the background signal that tells you where fixed rates are headed, even before the headlines catch up.
Should I wait for rates to drop?
Honestly, nobody knows when rates will drop. Markets could ease, or they could tighten further. What we do know is that while you wait, today's rate is not guaranteed to still be there. If the numbers move up, waiting costs you instead of saving you. That is why pre-approval is the smarter play: it protects today's terms while you keep looking.
How do I lock in a rate before I find a home?
You get a mortgage pre-approval. A lender reviews your finances, tells you exactly what you can afford, and holds today's rate for a set window, usually 90 to 120 days, while you shop. It does not commit you to anything, and it takes the guesswork out of your budget. M2 Mortgage Team walks buyers through it in plain language.
How much do I need for a down payment in Toronto?
In Canada, the minimum down payment is 5% of the first $500,000 of the purchase price, plus 10% of the portion between $500,000 and $1,499,999. For homes priced at $1.5 million or more, the minimum is 20%. If you put down less than 20%, mortgage default insurance is added to your costs, and a lender can show you exactly how that changes your numbers.
Ready to see it for yourself?
Book a viewing at 630 Rogers Rd #21, text Tory at 289-814-TORY (8679), or get pre-approved first with M2 Mortgage Team so you know exactly where you stand. No pressure, just straight answers.
Rate commentary reflects broad market conditions and is general context, not a rate promise or a prediction. Mortgage rates and down payment requirements vary by lender and situation, so always confirm the current numbers with a licensed mortgage professional.